In this article
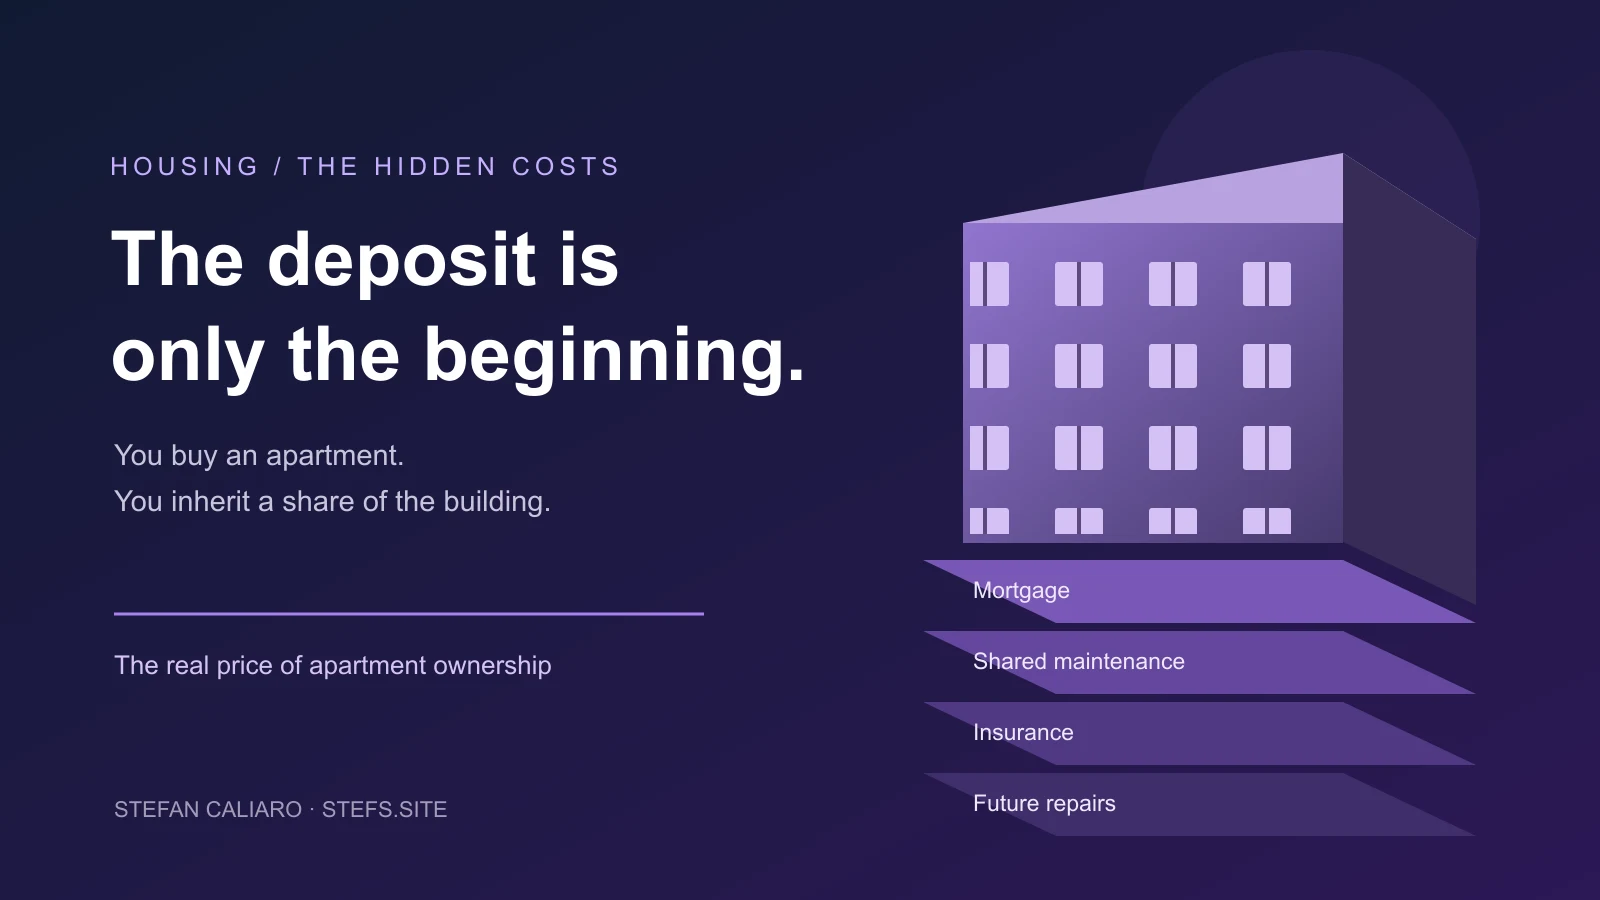
Australia's housing debate usually follows a familiar story: save the deposit, qualify for a loan, get the keys, and finally enjoy some security. The struggle is getting through the front door. What happens afterwards is treated as the manageable part.
For apartment buyers, that is an incomplete picture. Mortgage repayments are only one commitment. You also enter a compulsory financial relationship with the other owners in your building, sharing responsibility for infrastructure whose condition and future costs may be difficult to assess at an inspection.
The question is not only whether you can afford to buy the apartment. It is whether you can afford the building you are buying into.
That distinction matters even more when savings have already been stretched by years of rising living costs, and confidence in a stable career is becoming harder to take for granted. Getting the keys can change the form of housing insecurity without making it disappear.
The 5% deposit trap: getting in sooner, with little room for surprises
The Australian Government 5% Deposit Scheme offers a real benefit: eligible first-home buyers can purchase with as little as a 5% deposit, without lenders mortgage insurance, through a government guarantee supporting part of the loan. From 1 October 2025, the expanded scheme removed income caps and limits on places and increased property-price caps. Eligibility requirements, the applicable price cap and the lender's credit assessment still matter; the official scheme guide explains those conditions. Housing Australia explains the expansion.
I understand why that is attractive. If saving a deposit takes years while rents and prices keep rising, getting into a home sooner can change someone's life. My concern is what happens when the deposit becomes the finish line in the conversation, rather than the starting point for assessing ownership costs.
Consider a simplified, hypothetical purchase: a $600,000 apartment, a $30,000 deposit and a $570,000 loan. A 5% fall in the property's value would equal the original deposit. That illustration ignores principal repayments and transaction costs; it shows how little initial equity separates a highly leveraged buyer from owing as much as the property is worth. Equity is also different from cash available to pay a bill next month.
That is the “trap” I mean: starting with high debt and assuming admission to ownership means being financially secure within it. The scheme does not cause building defects. But someone who has struggled to save even 5% may have very little left when the owners corporation needs a five-figure contribution. The mortgage assessment and the building assessment need to be part of the same decision.
The building's appearance does not tell you what you are buying
Before comparing quarterly levies, I would check the legal title. Most apartments are strata, and villas and townhouses can be strata too. Some older flats use company title: the company owns the land and building, while shares provide rights to occupy a particular flat. Community-title estates can combine individually owned lots with shared association property. State Library of NSW's guide to property interests.
Other developments that look like a single complex contain separately Torrens-titled properties. An ordinary non-strata Torrens property generally has no owners corporation collecting strata levies in the same way, although easements, shared services or contractual obligations can still create costs. Stratum arrangements also exist, particularly where different parts of a building have separate ownership and shared facilities. The contract and registered plans, not the listing's description, need to explain the arrangement. Council guidance on stratum subdivision.
A freestanding-looking villa can therefore carry strata levies, while an attached-looking home can sometimes have no strata at all. “Torrens” and “strata” are not perfect legal opposites, since strata interests also sit within the Torrens registration system; the practical question is whether this purchase brings owners-corporation membership and shared property obligations. I would want my solicitor or conveyancer to spell out exactly what I own, what I share and who can require me to contribute.
The affordable unit that isn't necessarily affordable
Buying a unit instead of a freestanding house can be a sensible compromise. A smaller property, a different suburb or fewer amenities might put ownership within reach. Apartments can also offer a location and lifestyle that buyers actively prefer.
The problem is treating the advertised price and quarterly levy as a complete account of affordability. Neither tells you, on its own, whether the building has enough money to meet its obligations or whether expensive repairs have been postponed.
Depending on the scheme, you share responsibility for roofs, façades, waterproofing, lifts, basements, fire equipment and other common property. These assets age whether or not owners have budgeted for their replacement. When reserves are inadequate, the cost can return through higher contributions or a special levy.
NSW strata schemes generally maintain an administrative fund for everyday expenditure and a capital works fund for longer-term work. Their 10-year capital works plan is meant to connect foreseeable maintenance with the money collected from owners. NSW guidance on strata finances; capital works planning resources.
This makes very low levies an ambiguous selling point. They may reflect a simple, well-maintained building with modest running costs. They may also reflect years of collecting less than the building will eventually need. The useful question is not whether a levy looks cheap, but whether it is credible for that particular property.
Unit entitlement: the number that keeps appearing on your bills
Strata levies are not normally an equal split between apartments. In NSW, ordinary contributions and special levies are generally allocated in proportion to each lot's unit entitlement, recorded on the strata plan. A larger entitlement means a larger share of the amount being raised. NSW Government guidance on levies.
Unit entitlement also determines your proportional interest in common property. It can affect voting strength, although not every decision is weighted that way: ordinary resolutions generally start with one vote per lot, while special resolutions and polls use unit entitlements. NSW buyer guidance; how voting works.
This is where the advertised quarterly fee can conceal a lasting affordability issue. Two apartments with similar present-day values can have different entitlements established much earlier. Their relative values may have changed, or the original allocation may warrant investigation. Similar prices today do not, by themselves, prove that an older allocation was legally unreasonable. But a buyer inherits its financial consequences unless it is validly changed.
A hypothetical difference that compounds over time
Imagine a scheme with 1,000 total entitlement units. One apartment has 10 and another has 15. If the owners corporation raises $200,000 for the year, their proportional contributions are $2,000 and $3,000. For a $1 million special levy, the same fractions produce $10,000 and $15,000.
The second owner pays 50% more in this illustration. If that $1,000 annual difference continued for 20 years, it would total $20,000 before any special levies or increases. These are illustrative calculations, not a documented building or a prediction. They show why the allocation matters even when this quarter's payment feels manageable.
If the lots are genuinely comparable, I would want the historical basis explained. A higher entitlement is not automatically unfair: size, position and other value differences can justify it. Equally, a figure should not escape scrutiny simply because it has appeared on the plan for decades.
Alongside “What are the quarterly fees?”, ask: “What is my unit entitlement, what are the entitlements of comparable lots, and why?”
The November 2016 line buyers rarely hear about
In April 2016, NSW Land and Property Information released the draft Strata Schemes Development Regulation and its Regulatory Impact Statement for consultation. On 30 November 2016, the Strata Schemes Development Act 2015, Strata Schemes Management Act 2015 and associated regulations commenced. Registrar General's commencement notice.
The new framework required a qualified valuer to determine unit entitlements when establishing a scheme and for relevant subdivisions. For an ordinary strata plan without a development lot, Schedule 2 sets out apportionment on a market-value basis at the prescribed valuation day. Special arrangements apply to development lots. Registrar General's explanation; Development Act, Schedule 2.
That did not invalidate every earlier strata plan or automatically revalue and replace every older entitlement schedule. Two similar buildings can still carry allocations originating in different eras. The broader lesson is uncomfortable: improving how new schemes begin does not necessarily resolve the arrangements existing owners already live with.
There is a way to challenge an unreasonable allocation, but it involves evidence and a legal process. Section 236 allows NCAT to order reallocation on specified grounds. NCAT's guidance calls for a qualified valuer's certificate addressing each lot's value when the scheme was registered, or at the relevant statutory point such as a change in permitted land use, together with the existing plan or title information. A current sales comparison alone is not a substitute. Management Act, section 236; NCAT's orders and evidence requirements.
For a prospective buyer, I would rather understand the allocation before signing than assume I can cheaply correct it afterwards. For an existing owner, professional valuation and legal advice can establish whether there is a viable challenge, rather than just a frustrating difference between neighbouring bills.
When the levy suddenly jumps
Someone responding to my original comment described an experience that captures the problem: the strata fees looked reasonable when they purchased, but the required contributions later proved substantially higher.
It is easy to respond with “you should have done more research”. Buyers should investigate, but that advice understates how much specialised information they are expected to interpret. A first-home buyer can spend months comparing mortgage rates, suburbs and government schemes without learning how to evaluate an owners corporation's finances.
A useful assessment has to connect several things. The balance in the capital works fund matters, but so does the work that balance is supposed to cover. Meeting minutes may reveal repeated water ingress, disputed repairs or engineering investigations. Insurance, arrears, contracts and litigation can change the picture again.
A hypothetical $600,000 apartment could come with a share of substantial future repair bills that is barely visible in the sales conversation. A renovated kitchen is easy to photograph. A maintenance backlog is much easier to miss.
Watch: Four Corners, The Strata Trap
ABC's September 2024 investigation examines how hidden charges, conflicts and weak oversight can affect apartment owners. It is a useful introduction to the gap between buying a private home and becoming financially dependent on the management of a shared building. The reporting concerns particular practices and cases, rather than proving that every strata scheme is dysfunctional.
Investigate the records before committing
My advice would be to put the owners corporation under the same scrutiny as the apartment. Arrange a professional strata records inspection and have your conveyancer or solicitor explain material concerns before you become legally committed. A report is useful evidence, not a guarantee that every defect or future liability has been discovered.
NSW Fair Trading's buyer guidance explains the value of a strata search and financial information about the scheme. I would also want to understand what several years of meeting minutes reveal, rather than relying only on a summary and the current levy figure.
Consider an illustrative sequence: one meeting requests waterproofing quotes, the next defers the work, and a later meeting commissions an engineer because the leak has spread. Any single entry might look routine. Together, they suggest a problem that has remained unresolved while its likely cost has changed.
This is why the boring documents deserve attention. They can tell you whether owners act on advice, whether budgets are realistic, and whether the same issue keeps returning without a funded solution. An inspection of the apartment itself cannot answer all of those questions.
The strata report is not a box to tick. It can contain hundreds of pages about the financial and physical history of the asset you are about to co-own. I would have an experienced strata solicitor or conveyancer review the contract and the important strata material before becoming unconditionally committed, with specialist building advice where the records reveal technical concerns.
That review should connect the entitlement schedule, AGM and committee minutes, levy history, fund balances, arrears and capital works forecasts with insurance, engineering and defect reports, litigation, special levies, strata loans and major contracts. Fire safety, waterproofing, cladding, completion and warranty dates, and planned works deserve explicit attention. Professional review reduces risk; it cannot reveal every hidden defect or guarantee future costs.
Formal records also cannot tell you everything about living there. I would search the building or address in resident communities, including Tenant Reviews on Facebook, and speak to people who live in the building where possible. Those accounts are anecdotal leads, not verified findings. Check anything concerning against the records, the relevant reports and professional advice.
New apartments aren't automatically the safe option
A new building can feel reassuring because everything looks fresh. But modern complexes may contain expensive shared equipment: lifts, pumps, mechanical ventilation, electronic access, fire systems, pools and gyms. Those facilities can be valuable; they also create maintenance and replacement obligations.
Defects are a separate concern. Building Commission NSW's 2025 research found serious defects in 53 per cent of the buildings surveyed. Waterproofing was the most common category at 22 per cent, followed by fire-safety systems at 16 per cent. Building Commission research and methodology.
The scope matters. There were 520 completed surveys, covering Class 2 strata buildings of four storeys or more registered between July 2018 and June 2024. These are not findings about every apartment in NSW. The Commission also reports lower serious-defect rates in buildings registered during 2022–2024 than in the earlier cohorts.
The sensible conclusion is that newer construction still deserves scrutiny. Older buildings need a different kind of attention: the condition of roofs, concrete, pipes, windows and balconies, along with the accumulated consequences of previous maintenance decisions. There is no construction year that removes the need to investigate.
Watch: Site Inspections on a first-home buyer's experience
The Site Inspections channel adds a practical inspection perspective to this discussion. Its episode below focuses on a first-time home buyer's experience, making it a useful companion to the question of what buyers can discover beyond a property's presentation.
I would watch it as an individual case study, alongside the broader Building Commission research above. For an apartment purchase, the relevant lesson is to investigate both the physical building and the owners corporation's records: an inspection and a strata search provide different parts of the picture.
The six-year warranty cliff
A new apartment has another clock running behind its clean finishes. NSW statutory building warranties generally allow six years for major defects and two years for other defects, measured from completion of the work, not the day a later buyer acquires the apartment. A breach becoming apparent in the final six months can allow a further six months to bring proceedings in the circumstances covered by the legislation. The dates and available action need prompt, specific advice. NSW guidance on statutory warranties; Building Commission explanation of late-emerging defects.
I use “warranty cliff” as an editorial description of the funding risk, not a formal legal term. A sixth anniversary does not automatically trigger a levy, and it does not erase every possible remedy. Building Commission NSW notes that serious common-property defects in buildings up to ten years old may warrant a complaint and regulatory intervention. Applicable rights, deadlines and the ability to recover from the responsible parties depend on the circumstances. NSW strata repair guidance.
Nevertheless, unresolved work does not disappear when an enforcement avenue closes. NSW guidance warns that older buildings may need to fund defect repairs through their capital works fund. In practical budget terms, that can mean using reserves, increasing contributions, borrowing or raising special levies. A theoretical claim is also not the same thing as cash available to pay a contractor.
A low levy during a development's first few years therefore needs context. Will the budget remain credible as lifts and pumps age, façades need work, waterproofing problems emerge, insurance history develops and shared systems require replacement? Early estimates eventually meet an actual maintenance history. I would want a plan that survives that transition, rather than reassurance based solely on how inexpensive the building has been so far.
When home ownership means being ordered out of your home
The stories from Opal Tower and Mascot Towers particularly affected me because they make the risk human. These are extreme examples, not a description of every modern apartment building. But they expose a possibility that mortgage calculators cannot adequately convey: ownership can continue while access to your home stops.
Opal Tower: Christmas Eve 2018
On 24 December 2018, reports of cracking prompted the evacuation of Opal Tower at Sydney Olympic Park and its surrounds. It was essentially brand-new: ABC reported that the building had opened only four months earlier. ABC's initial report.
About 3,000 people were initially evacuated from the building and surrounding area, not all from inside the tower. ABC subsequently reported that 51 apartments were considered unsafe for residents to return to. Its Christmas coverage described families separated from their belongings and familiar routines, including a child worried about a favourite teddy left upstairs. ABC's report on displaced residents.
Residents were then asked to leave again for further investigation, with the builder arranging alternative accommodation but unable to guarantee the return date. ABC's follow-up on the second evacuation.
Imagine reaching settlement on a near-new Sydney apartment, believing the difficult part is behind you, and spending Christmas unsure whether you can safely stay in it. The disruption is not just financial. Home is where children sleep, routines work and belongings remain within reach. Losing that certainty is a housing crisis even when your name is on a title.
Mascot Towers: displaced, and asked to pay again
On 14 June 2019, structural cracking led to residents being evacuated from Mascot Towers, a Sydney complex of more than 130 apartments. Families had to find somewhere else to sleep with little certainty about when they could return. ABC's evacuation coverage.
ABC's longer resident story recorded Masa Tatewaki's distress after being prevented from re-entering while his dogs were still inside. Another resident, Matthew Harris, explained that he did not have local friends or family to stay with and did not know where he would live in the coming days or months. Those details matter: being told to leave assumes you have somewhere else to go. ABC: residents confused and in tears.
Then came the financial sting. On 20 June, ABC reported owners agreeing to a $1 million levy while residents remained displaced. It was a contingency fund for initial engineering advice and building stabilisation, not a final price for fixing everything. Owners were being asked to contribute before the full path back home was clear. ABC's report on the levy.
Being unable to live in your apartment does not, by itself, suspend the mortgage or the building's need for money. An owner can face displacement and a repair levy at the same time.
That is the collision this article is concerned with. The household budget assumes a functioning home; the building's budget suddenly requires urgent intervention. Meanwhile, the resident needs somewhere to sleep. These reports describe events in 2018 and 2019, rather than asserting that every original resident remains displaced today.
Neither case means every apartment is unsafe or that due diligence can predict every emergency. They explain why a building's condition, funding and response to warnings deserve attention before purchase, rather than being treated as someone else's administrative problem.
Inflation follows you through the front door
The person replying to me also raised the relentless feeling of rising strata costs. There are real economic pressures behind some of those increases, even where a scheme is managed competently.
The Insurance Council of Australia identifies more expensive repairs and building supplies, reinsurance costs and extreme-weather losses as contributors to strata insurance increases. It also calls for better fee transparency and building risk management. That is the industry's explanation, and it should be read alongside scrutiny of commissions and procurement, rather than used to excuse every increase. Insurance Council policy statement.
A building saving for a roof replacement is exposed to the future cost of that roof, not simply the household inflation figure. If its plan relies on old estimates and its contributions do not keep up, a healthy-looking bank balance may buy less work than owners expect.
There is also a distinction between inflation slowing and prices falling. Slower increases do not restore the purchasing power already lost unless incomes catch up. For a household that has spent years absorbing higher bills, the emergency fund available for a special levy may already be thinner than it once was.
Buying a home therefore does not remove inflation from your life. It changes which costs you face and how much flexibility you have when they arrive.
The governance problem is also an affordability problem
Strata places part of your financial future in collective hands. You might want preventative maintenance while other owners prefer to delay spending. Some owners may have substantial savings; others may already be struggling with their mortgage. Their incentives and ability to pay will not always line up.
Good volunteer committees can do a great deal with limited time. But a disengaged scheme can drift into trouble even without dramatic misconduct. Repeatedly postponing a difficult decision may keep this year's levy lower while making the eventual repair more disruptive and expensive.
There are also documented concerns about professional management. NSW Fair Trading's February 2025 release on the independent Netstrata examination described potential breaches involving procurement and commission disclosure in a sample of 60 schemes. Those findings should be described accurately as potential breaches, rather than treated as proof of every allegation about the industry. Fair Trading's report announcement.
Fair Trading subsequently announced criminal proceedings in 2026. Its announcement describes allegations, not a final finding of guilt. Fair Trading's prosecution announcement.
Tenants can also notice governance failures long before they appear in a sales brochure. Repeated lift breakdowns, unreliable hot water, faulty garage doors, mould, noise, leaks, security concerns and short-term letting disputes can reveal how management responds to everyday problems. Communities such as Tenant Reviews provide another way to look for these experiences. I would treat recurring accounts as questions to investigate, not findings against a building or manager, and verify them against dated records and responses.
A shorter watch: the insurance investigation
This ABC News report introduces the insurance arrangements examined by Four Corners. It provides context for a practical question owners should be able to ask: who receives money from this policy or contract, and has that relationship been clearly disclosed?
Reform matters, but owners still need understandable information
It would be inaccurate to say governments have done nothing. NSW has introduced reforms in stages, and some of the details have changed since the Four Corners investigation aired.
From April 2026, new or revised 10-year capital works plans must use the standard form. Existing plans do not all need immediate replacement. Additional requirements cover independent review and certification of initial maintenance schedules and levy estimates for relevant new multi-storey schemes. From 1 October 2026, new and returning committee members must complete annual training within three months of appointment. NSW guide to the changes.
The NSW Productivity and Equality Commission's 2026 commissions review also found that a move towards fee-for-service remuneration could improve transparency, competition and trust while lowering costs. That is a reform assessment, not a statement that commissions have already been universally abolished. Strata Commissions Review.
Better forms and disclosure are useful, but they need to translate into information ordinary owners can understand and act on. A document can technically disclose a risk while leaving a first-home buyer with little sense of its likely cost or urgency. As apartment living expands, that gap deserves as much attention as the number of dwellings being approved.
A thirty-year mortgage assumes a lot about your working life
A heavily mortgaged apartment owner depends on more than the value of their property. They also depend on continued income, or enough reserves to manage an interruption. A major repair bill can become much harder to absorb if it arrives during a redundancy, reduced hours or a prolonged search for suitable work.
AI adds another source of uncertainty, although predictions deserve care. Jobs and Skills Australia's 2025 national study found generative AI was more likely to augment human work than replace it outright, while anticipating changes in tasks and skill requirements. That is an assessment of the broader labour market, not a guarantee about any individual's role or earnings. JSA's national AI study.
Taking on a 25- or 30-year mortgage means making assumptions about decades of income. Nobody can eliminate that uncertainty, but buyers should have a clearer view of the building liabilities they are adding to it. A budget that works only while employment, interest costs and maintenance all remain favourable deserves a second look.
Buying into a small government
Perhaps the most useful way to think about strata is that you are joining a small private government attached to your home. It raises levies, maintains infrastructure, sets budgets, hires suppliers and makes collective decisions. Your ability to influence it matters, but it is not the same as having sole control.
The comparison helps explain why a purchase deserves more than an assessment of the apartment's layout. You are also assessing an institution: its records, decision-making, finances and willingness to deal with problems. A good scheme can make shared ownership efficient and manageable. A badly run one can undermine the security the purchase was meant to provide.
I would therefore replace “buy a unit, it's cheaper” with a more complete proposition: compare the purchase price, the realistic ongoing costs, the building's condition and the quality of its management. An apparently cheaper apartment can become the more expensive choice if those other parts are ignored.
The sale price is only the first layer
We spend enormous energy asking whether young Australians can scrape together a deposit. I think we need to spend more of it asking what they inherit when they succeed.
A buyer can enter through a government-backed 5% deposit scheme, acquire a lot with a historical entitlement allocation, discover approaching warranty deadlines, and then face rising capital works contributions or a special levy. Their ability to change the outcome remains shared with the other owners, under the scheme's voting rules. No single item in that sequence has to be extraordinary for the combined financial pressure to become serious.
The progression is simple enough to deserve a place in every buying conversation: the deposit gets you through the door; the title defines what you bought; unit entitlement helps divide the bills; warranty and recovery deadlines affect who may fund defects; governance shapes what happens next.
That is why the advertised sale price is nowhere near a complete account of apartment ownership. A more honest affordability discussion would make these obligations visible before the buyer has committed their savings and future income.
Before buying: the questions I would want answered
This is the checklist I would take into discussions with a strata inspector and an experienced solicitor or conveyancer before becoming unconditionally committed:
-
What title am I buying? Confirm strata, ordinary non-strata Torrens, company, community or another arrangement, including shared services and the exact lot boundaries.
-
What is my unit entitlement, and why? Compare the registered schedule with comparable lots and ask whether any historical allocation needs qualified valuation advice.
-
Which deadlines matter? Establish completion dates, applicable warranties, known claims and any imminent enforcement deadlines. Do not assume the clock restarts at purchase.
-
What does the financial position really mean? Compare current reserves and contributions with planned expenditure, rather than treating the bank balance as a standalone sign of health.
-
What has remained unresolved? Read several years of AGM and committee minutes for recurring problems, delayed work and decisions that keep being revisited.
-
What could require additional funding? Understand proposed projects, previous special levies, unpaid contributions and any significant disputes or proceedings.
-
What is the physical evidence? Review available defect and engineering reports, with particular attention to the systems and materials present in that building.
-
Who is being paid, and on what terms? Examine major contracts, insurance arrangements and disclosed relationships so that service costs can be questioned meaningfully.
-
What do residents report? Search the building or address on Tenant Reviews, local Facebook groups and resident forums. Verify concerns against strata records, meeting minutes, defect reports and professional advice.
-
How would this fit my own finances? Consider an income interruption alongside higher ownership costs, with advice appropriate to my circumstances.
A records review and a physical building assessment answer different questions. Neither should be confused with a promise that nothing expensive will go wrong. The aim is to make a better-informed decision before committing, rather than trying to interpret the obligations after settlement.
The housing crisis doesn't end at settlement
None of this is an argument against apartments. Well-run schemes can provide good homes, share maintenance efficiently and make better use of scarce urban land. Nor is renting free of insecurity or rising costs.
The argument is that ownership should not be treated as an automatic escape from financial vulnerability. An apartment owner can face mortgage repayments, council rates, rising levies and unexpected repairs at the same time as a difficult job search or a reduction in earnings.
For some people, buying will still be the right decision. For others, waiting may reflect a reasonable assessment of those obligations rather than a failure of ambition. A housing debate that measures success only by entry into ownership misses that distinction.
We should ask how more people can get through the front door. We should also ask whether they can sustainably carry the responsibilities waiting on the other side. The deposit is the entry cost. Affordability has to last longer than settlement day.
Useful resources
The legal examples in this article concern NSW; strata rules differ across Australia.
-
Building Commission NSW: 2025 Strata Defects Research Report.
-
Housing Australia: expansion of the 5% deposit scheme from 1 October 2025.
-
Registrar General: 2016 regulation consultation and commencement and new strata legislation commencing 30 November 2016.
-
Strata Schemes Development Act 2015, Schedule 2; Strata Schemes Management Act 2015, section 236; NCAT evidence requirements for reallocation.
-
NSW statutory warranty guidance and strata building repairs.
-
ABC: Opal Tower's Christmas Eve evacuation and residents asked to leave again.
-
ABC: Mascot evacuation, residents' experiences and the $1 million levy.
Thanks for reading. About reader stats
Get in touch ↗
Join the conversation
No account needed. Keep comments thoughtful and respectful. Your first comment is held for approval.
View earlier GitHub discussions ↗